European Formwork Buyers Book Q1 Loads as Suez Sailings Return
Carriers are restoring Asia–Europe Suez sailings this month. European formwork buyers can book Q1 film-faced loads from Vietnam for shorter transit and clearer schedules.
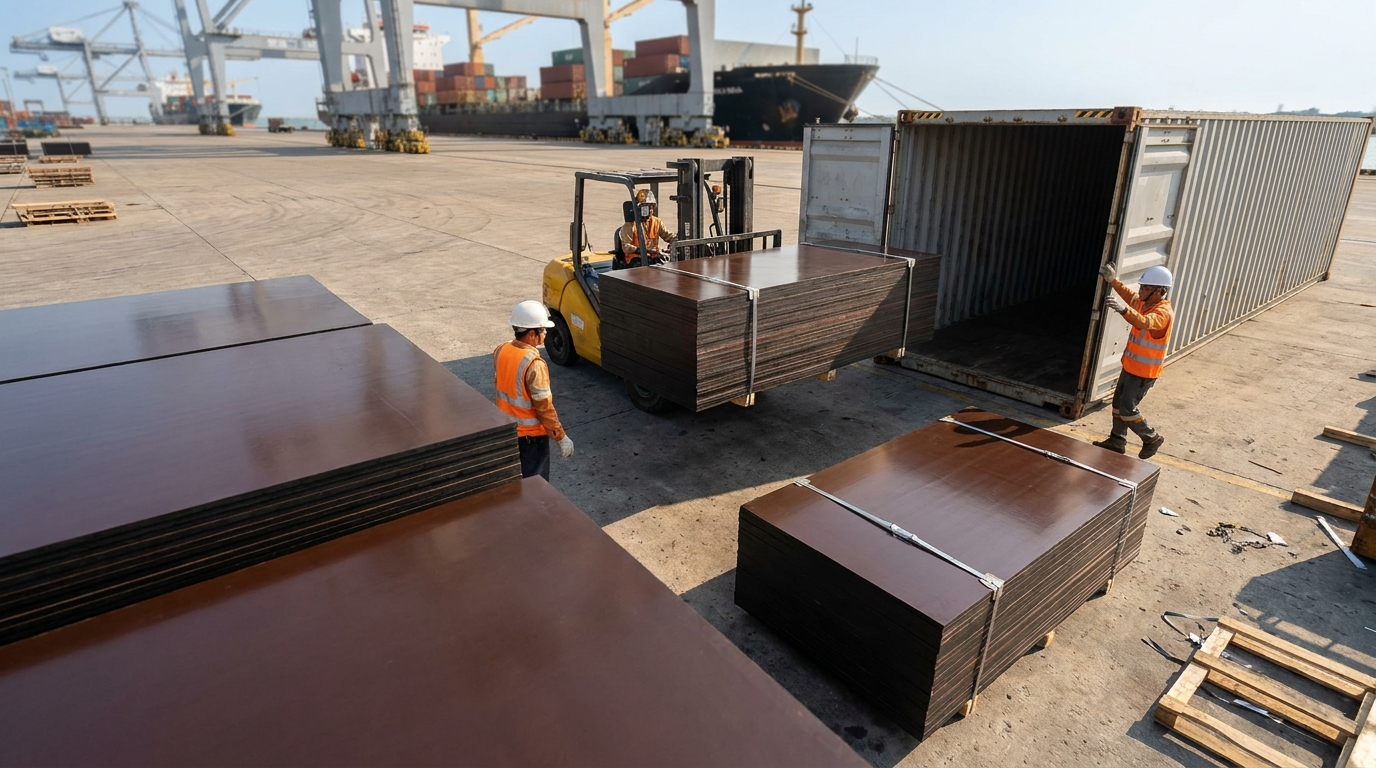
Carriers are putting Asia–Europe and Asia–Mediterranean loops back through the Suez Canal this month, and that shortens the clock for formwork plywood headed to European yards. Evergreen is sending ships through Suez on Ocean Alliance services from early November, Premier Alliance partners plan Mediterranean Suez sailings next month, and industry trackers say the three main alliances plus MSC are on track for a full Suez return by the first quarter of 2027. For a buyer who sources film-faced or phenolic formwork from Vietnam, the practical change is simpler schedules and a better chance of January and February arrivals landing closer to the pour calendar.
Suez space opens for Q1 formwork
The Loadstar reported on 3 November that Evergreen will put the Ever Eon and Ever Edit on eastbound Suez transits on the NEU7/CES service on 7 and 11 November, with the Ever Gifted following on an Asia–Mediterranean MD2 sailing on 16 November. Yang Ming and HMM plan to join Premier Alliance Suez crossings in December, including a revised MD1 rotation that adds Sokhna for Red Sea cargo. Israeli carrier Zim remains the main holdout still routing around the Cape of Good Hope.
Lloyd’s List Intelligence figures, summarised by World Ports on 8 November, show nearly 3.4 million teu of containership capacity moved through Suez in the four weeks to late October, more than double August levels. Twenty-four megamax ships above 20,000 teu used the canal in October, almost double September. C.H. Robinson’s November ocean update adds that by late October about 30 of 52 tracked westbound loops and 32 of 57 eastbound loops had resumed Suez, while the count of ships still diverted around the Cape had fallen to roughly 180 from an average near 350 over the prior two years.
Shorter round voyages release vessel and container capacity without adding ships. That can soften Asia–Europe spot rates over the next few weeks, and it also means booking windows for Q1 formwork need watching now rather than after Christmas. North European gateways may see bunched arrivals while Cape voyages and Suez voyages overlap, so a confirmed sailing still matters more than a headline rate.
Freight from Hai Phong
Drewry’s World Container Index for week 45 (assessment dated 5 November, reported 6 November) eased 1% to a composite $4,389 per 40ft container. The index is a Shanghai-composite benchmark. Vinawood uses those lane prints as Asia context for planning from Hai Phong, our home port for export loads: about $7,540 to the US West Coast, about $9,300 to the US East Coast, about $3,620 to Northern Europe, and about $4,170 to the Mediterranean, per 40ft. Shanghai–Los Angeles held at $7,539, Shanghai–New York fell 3% to $9,303, Shanghai–Rotterdam eased 2% to $3,615, and Shanghai–Genoa was flat at $4,166.
Panama Canal operations stay workable for US East and Gulf Coast routings, with 33 daily transit slots and a 49-foot authorised draft, according to C.H. Robinson. Reservations still matter for a guaranteed transit date. Middle East security remains uneven: more Asia–Europe services are using Suez again, yet Hormuz and Gulf calls carry war-risk and congestion surcharges, and alternative gateways such as Jeddah, King Abdullah Port, Khor Fakkan and Fujairah can add handling time.
Currencies and North American pours
European buyers pay for Vietnam plywood in US dollars. The ECB euro reference rate was $1.1165 per euro on 6 November, with a November average so far of $1.1210. A firmer euro against the dollar trims the euro cost of a dollar-priced FOB invoice; a softer euro does the opposite. Bank of Canada noon rates put the US dollar near 1.41 Canadian dollars in early November, so Canadian importers still feel a firm USD in landed cost.
US single-family builder sentiment is soft. The NAHB/Wells Fargo Housing Market Index fell to 29 in October, the lowest reading since June 2012, with buyer traffic at 18. Mortgage rates above 7% and high material costs are keeping many buyers on the sidelines. That does not erase formwork demand on projects already funded. Where pours are still on the calendar, importers who lock December and January container space keep price and schedule risk off the critical path.
We’d treat the Suez restoration as a schedule story first and a rate story second — the shorter routing helps Q1 planning even before spot levels settle.
Mill weather in central Vietnam
Northern Vietnam is entering its first widespread cold spell of the season, while central provinces face heavy rain through about 12 November. Tuoi Tre, citing the National Center for Hydro-Meteorological Forecasting, expects 250–450 mm in Hue, Da Nang and eastern Quang Ngai, with isolated totals above 700 mm. Wet logs and peeler blocks slow veneer drying and can tighten short-run mill calendars. Buyers with December loadings should confirm production slots early rather than assume every mill can absorb a weather delay.
Outlook
Suez restorations, Hai Phong planning freight near the Drewry Asia prints above, and European FX around $1.12 per euro all point to the same buyer move: put Q1 formwork on paper while sailings are being rewritten. US residential sentiment stays cautious, so North American programmes that are still pouring should book space against the winter schedule rather than wait for a clearer HMI print. See also our 2 November brief on December space. For film-faced and formwork grades from Vietnam, request a quote while November capacity is still being allocated.
About Vinawood
Vinawood is a Vietnamese plywood manufacturer established in 1992. We ship about 5,000 containers a year to 55+ export countries, and every formwork and film-faced panel goes through a 12-step production process and 100% individual sheet inspection. Certifications include ISO 9001, FSC-COC, PEFC, EN 13986 CE marking and UKCA, the wood is plantation-grown, and an EUDR evidence pack is available on request for European orders. For Q1 formwork loads, request a quote.
Category
market-insights
Related Markets
Related Countries
Related Products
▶Sources & References (8)
- Drewry: The World Container Index decreased 1% this week 45-2026 — World Ports Organization / Drewry (2026-11)
- Major liners set to resume all Asia-Europe services through Suez — The Loadstar (2026-11)
- Evergreen joins accelerating liner return to Suez — World Ports Organization (2026-11)
- Ocean Shipping Freight Market Update November 2026 — C.H. Robinson (2026-11)
- Builder Sentiment Falls on Rising Rates — NAHB (2026-10)
- ECB Euro Reference Rates, November 2026 — ECB via GlobalMacro.expert (2026-11)
- USD to CAD Rate November 2026 — Bank of Canada — Bank of Canada via Sched3 (2026-11)
- Central Vietnam braces for torrential rain of over 700mm — Tuoi Tre News / NCHMF (2026-11)