Residential Formwork Buyers Keep Booking Q4 Pours
Residential formwork buyers keep booking dated Q4 pours after August starts rebound and new-home sales up 6.4%. Hai Phong USWC ≥$7,838 / USEC ≥$10,373.
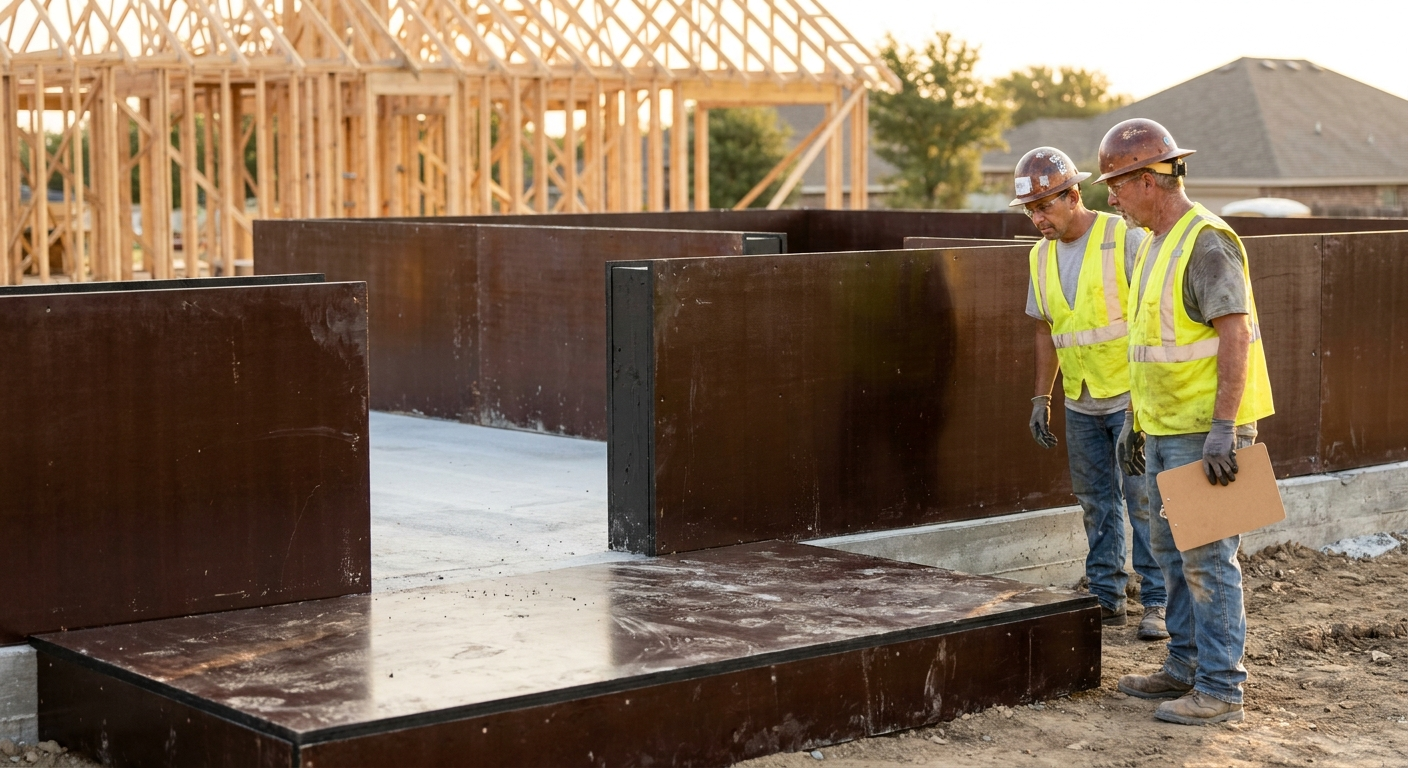
Residential formwork buyers are still placing orders against dated Q4 pours. Last week’s August single-family starts rebound (+7.6% to 918,000) is the print yards already booked are working from. August new-home sales rose another 6.4% to a seasonally adjusted 684,000. Builder sentiment is quieter — September’s NAHB/Wells Fargo HMI printed 32, Reuters reported on 16 September — but the sheets for pours already on the calendar still move.
Our 21 September brief led on that starts rebound. It still matters for residential gang schedules with pour dates through year-end. An HMI of 32 is context on mood, not a reason to cancel cover for the next six to eight pour weeks. Cover the dated work. Leave loose Q1 volume until traffic and mortgage prints give a clearer read.
Freight sits second this week. Drewry’s World Container Index eased 1% to $4,468 per 40ft on 24 September on Asia–Europe softness, Daily Cargo News reported on 25 September. Transpacific cancelled sailings for next week rose to 15 from nine. From Hai Phong, a 40HC to the US coasts still plans at or above Drewry’s matching Shanghai coast figures — the floor for anyone buying film-faced plywood out of northern Vietnam.
Starts rebound still feeds booked Q4 pours
An HMI of 32 is a survey of builder mood, not a starts count. Purchasing managers who raised Q4 formwork orders after the Census single-family rebound still have active pour calendars to feed. Current sales components and buyer traffic stayed thin on the NAHB release, with mortgage rates the usual drag. Higher construction costs and labor shortages sit in the same mix.
August new-home sales add a demand note beside the starts print. Sales of new single-family houses rose 6.4% to 684,000, Census and NAHB reported, while inventory stayed near 8.5 months of supply. More closings help the yards already on site. Heavy inventory keeps builders from racing to open brand-new slabs — it does not stop the pours already dated.
Plan against those dated pours. Do not stretch mill weeks as if HMI will snap back to 50 before year-end.
Asia–US container rates and Golden Week cancelled sailings from Hai Phong
Drewry’s WCI at $4,468 is a Shanghai-composite benchmark. Treat it as direction, not as the Hai Phong freight rate a northern Vietnam mill quotes against. On the 24 September assessment, Shanghai–Los Angeles rose 2% to $7,838 per 40ft. Shanghai–New York held at $10,373. Shanghai–Rotterdam fell 4% to $3,485 and Shanghai–Genoa fell 5% to $3,835. For buyer planning with no fresh Hai Phong print this week, a 40HC from Hai Phong to the US West Coast sits at or above $7,838, and to the US East Coast at or above $10,373. Soft whispers under those bars stay off the planning sheet.
Carriers announced 15 Transpacific cancelled sailings for next week, up from nine. A cancelled sailing (carriers also call this a blank sailing) means the line drops that voyage; the ship does not run that week. It is not a vessel leaving empty. Seven Asia–Europe cancelled sailings were announced, up from three. Drewry still expects rates to ease ahead of China’s Golden Week holiday in early October even as cancelled counts rise, because recovering Suez capacity is adding space on Asia–Europe. Suez Canal transits rose from 41 in Week 37 to 48 in Week 38. Red Sea security risk and constrained Panama Canal capacity remain schedule risks on East–West services, not a reason to ignore the US coast bars above.
From our mill desk, we would lock the Hai Phong load week against those US West Coast and East Coast bars before treating a softer World Container Index average as a reason to wait. Europe’s cheaper Rotterdam and Genoa figures only help if the container stays on the week you bought.
SBV reference eases. Dollar FOB still rules the sheet.
The State Bank of Vietnam set the central rate at 25,632 VND per USD on 28 September, down nine dong from the prior week’s close, VietnamPlus reported. Vietcombank and BIDV listed morning buy/sell at 25,790 / 26,170. Most Vietnam mill FOB contracts invoice in dollars. A buyer converting euros, Australian dollars, or won into that invoice still feels the week’s move even when the panel list holds. Write FX as its own landed-cost line next to ocean and origin wait.
Phenolic Class 3 / EN 636-3 product such as Pro Form still belongs on exterior or long wet-storage pours. Form Extra remains a higher-melamine-content MUF panel in the EN 636-2 envelope and is not Class 3. Builder mood does not change the bond class on the RFQ.
What to do this week
Keep Q4 residential formwork against the pours already on the calendar. Use September’s HMI at 32 as short mood context beside last week’s single-family starts rebound, not as a stop order. Frame Hai Phong loads at or above $7,838 West Coast and $10,373 East Coast on the 24 September Drewry Shanghai coast figures. Keep the jump in Transpacific cancelled sailings and Golden Week capacity management as secondary freight risks. Convert FOB against the 25,632 central rate and the bank sell side you actually pay.
Keep film-faced and structural formwork lines on clean purchase orders so freight and FX stay readable next to glue class for the yard that will strip the sheet. For Q4 residential programmes that already have pour dates, book mill week and vessel week together while those dates are still live.
About Vinawood
Vinawood is a Vietnamese plywood manufacturer established in 1992, headquartered in Hanoi with factories in Hanoi and Bac Ninh. The mill ships more than 5,000 containers a year to 55+ export countries across Asia, the Americas, Europe, the Middle East, Africa and Australia, with film-faced and formwork panels built on a documented production process and individual sheet inspection. Core certifications include ISO 9001, FSC-COC, PEFC, EN 13986 CE marking, and EPA TSCA Title VI for US-bound orders. Wood is plantation-grown. For Q4 and Q1 formwork enquiries, request a quote.
Category
market-insights
Related Markets
Related Countries
Related Products
▶Sources & References (5)
- US homebuilder sentiment drops to 12-month low in September — Reuters (2026-09-16)
- Builder Sentiment Falls on Higher Interest Rates and Costs — NAHB (2026-09)
- World Container Index – 24 September 2026 — Daily Cargo News / Drewry (2026-09-24)
- New Home Sales Rise as Affordability Challenges Continue — NAHB / Census (2026-09)
- Reference exchange rate down 9 VND at week’s beginning — VietnamPlus / SBV (2026-09-28)