Cancelled Sailings Tighten Asia–US Container Space
Carriers cancelled eight Asia–US sailings next week. Frame Hai Phong public bars at or above Drewry’s Shanghai coast figures. July starts soft; SBV reference 25,607.
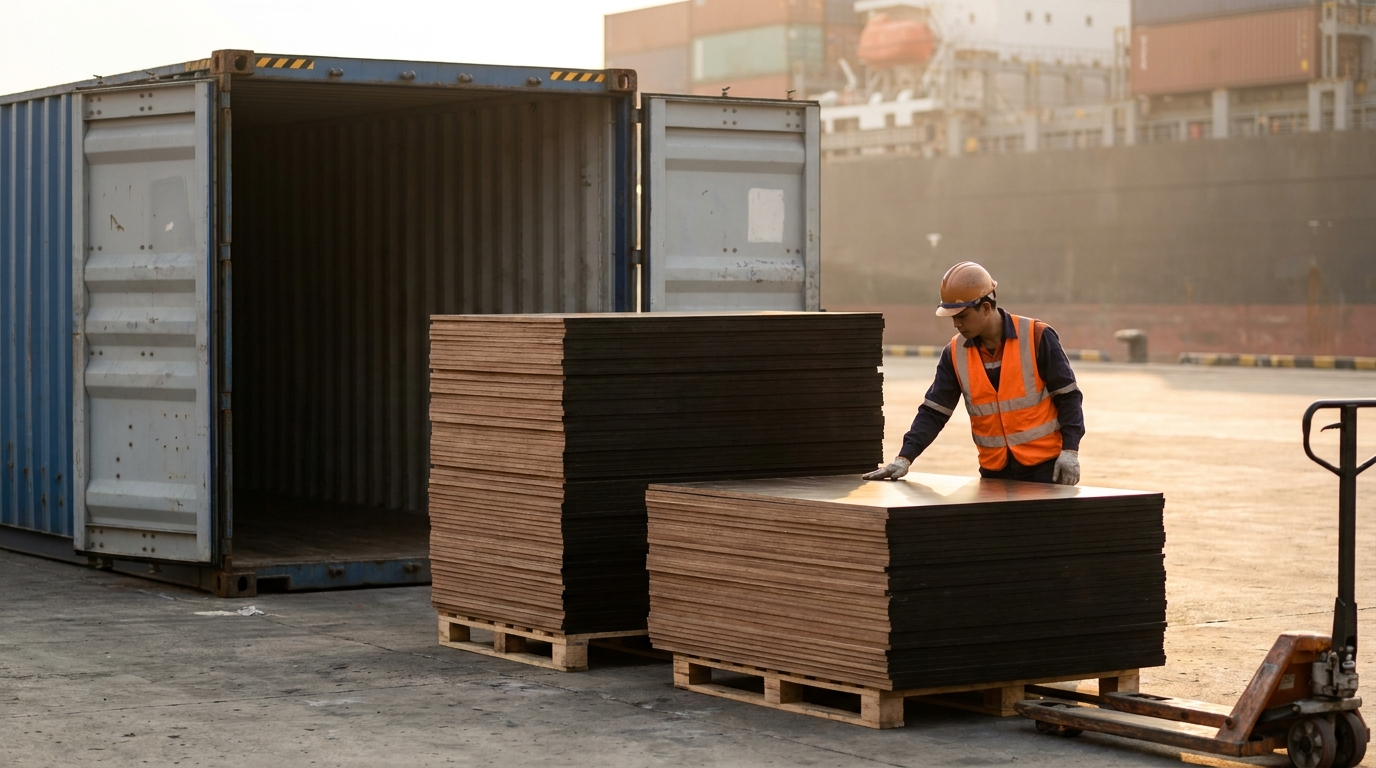
Carriers cancelled eight Asia–US sailings for next week, one more than the week before. A cancelled sailing — carriers also call this a blank sailing — is when the line drops a scheduled voyage, so that ship does not run that week. It is not a ship leaving empty. The container booked on it then waits for the next open week, or pays more to move earlier. That schedule risk shows up as extra inventory days for a formwork buyer, not as a neat move on Drewry’s average freight index. Asia–Europe cancellations rose from one to three in the same window.
Drewry’s World Container Index held at $4,476 per 40ft on 10 September, up about 0.2% from $4,465. Shanghai–Los Angeles rose 2% to $7,352. Shanghai–New York rose 1% to $9,726. Rotterdam fell 2% to $3,997 and Genoa fell 3% to $4,216. US coast rates firmed while Europe eased. A Hai Phong load week still has to compete for the same Asia–US space those Shanghai coast figures describe.
Our 31 August freight brief already treated a soft average as a poor reason to wait. This week the cancelled-sailing count is the sharper signal.
Cancelled sailings tighten Asia–US space from Hai Phong
Drewry’s World Container Index is a Shanghai-based average. It is useful for direction. It is not the Hai Phong freight rate a northern Vietnam mill quotes against. For buyer guidance, treat the public Hai Phong bar for the US West Coast as at or above the matching Drewry Shanghai–Los Angeles figure of $7,352 per 40ft, and the US East Coast bar as at or above Shanghai–New York at $9,726. Soft whispers around $5,200 on the West Coast are not a planning figure against those levels.
Eight Transpacific cancelled sailings for next week, up from seven, cut effective weekly slots on the main Asia–US lane that carries most Vietnam film-faced plywood into North America. Three Asia–Europe cancelled sailings, up from one, tighten the eastbound Europe services that still compete for the same Asia capacity. A rolled container costs more even when the published tariff looks flat. Book the mill production week first, then the vessel week, and only then stuffing — before arguing that the average “held.”
Shanghai average vessel wait improved from 94 hours in Week 35 to 64 hours in Week 36. That is a secondary Asia-network note, not a Hai Phong berth guarantee. Northern Vietnam load weeks still price against Transpacific space and the US coast bars above, not against a softer Shanghai anchorage snapshot.
US starts soft. Permits are firmer.
Privately owned housing starts ran at a seasonally adjusted annual rate of 1,239,000 in July, 12.4% below the revised June estimate, the Census Bureau reported on 18 August. Completions fell 9.1% to 1,212,000. Single-family starts were 808,000. Permits rose 5.0% to 1,443,000. A permit is not a pour, but it is the forward ticket that keeps formwork yards from emptying their stock blindly.
Quiet July starts do not automatically deliver cheaper Asia–US containers when carriers are still cancelling sailings to hold rates. Landed cost for a Q4 pour programme still has three rows: mill FOB, ocean freight, and the wait if the sailing is cut. The August New Residential Construction release is due 17 September. Until that data lands, plan against the July split of soft starts and firmer permits, and keep ocean space locked rather than waiting for housing to “save” the freight file.
SBV edges the reference. FOB conversion still moves.
The State Bank of Vietnam set the central rate at 25,607 VND per USD on 14 September, up 11 dong from the prior week’s close, VietnamPlus reported. Vietcombank’s morning buy/sell quotes sat near 25,730 / 26,110 and were unchanged on the morning of 14 September on that same report. Most Vietnam mill FOB contracts invoice in dollars. A European or Australian buyer converting local currency into that dollar invoice feels the week’s move even when the sheet price holds.
From our mill desk, we would rather lock the Hai Phong load week against the US coast public bars than reopen an FOB file every time the average wiggles two-tenths of a percent. Write the FX conversion as its own line on the landed-cost sheet next to ocean and origin wait. Phenolic Class 3 / EN 636-3 product such as Pro Form still belongs on exterior or long wet-storage pours. Form Extra remains a higher-melamine-content MUF panel in the EN 636-2 envelope and is not Class 3. A cancelled sailing does not change the bond.
What to do this week
Treat the eight Transpacific cancelled sailings as the lead risk for Asia–US formwork arrivals over the next fortnight. Price Hai Phong public guidance at or above $7,352 West Coast and $9,726 East Coast on the Drewry Shanghai coast figures, and ignore soft West Coast whispers that sit far under those bars. Hold mill production week and vessel space before the August Census housing release on 17 September rearranges anyone’s demand story. Convert FOB against the 25,607 central rate and the bank sell side you actually pay, not against last month’s memory.
For Europe services, the cheaper Rotterdam and Genoa figures only help if the container stays on the schedule you bought. Three Asia–Europe cancelled sailings this week are a reminder that a soft tariff can still miss the pour date. Keep film-faced and structural formwork lines on clean POs so freight, FX and glue class stay readable to the yard that will strip the sheet.
About Vinawood
Vinawood is a Vietnamese plywood manufacturer established in 1992. The mill ships more than 5,000 containers a year to 55+ export countries across Asia, the Americas, Europe, the Middle East, Africa and Australia, with film-faced and formwork panels built on a documented production process and individual sheet inspection. Core certifications include ISO 9001, FSC-COC, PEFC, EN 13986 CE marking, and EPA TSCA Title VI for US-bound orders. Wood is plantation-grown. For Q4 and Q1 formwork enquiries, request a quote.
Category
market-insights
Related Markets
Related Countries
Related Products
▶Sources & References (5)
- World Container Index – 10 September 2026 — Daily Cargo News / Drewry (2026-09-10)
- Drewry WCI Holds at $4,476 as U.S. Container Rates Rise and Europe Lanes Slide — Ship Universe / Drewry (2026-09-11)
- Monthly New Residential Construction, July 2026 — U.S. Census Bureau (2026-08-18)
- Reference exchange rate up 11 VND at week’s beginning — VietnamPlus / SBV (2026-09-14)
- SBV reference rate 14 September 2026 — VOV / VietnamPlus (2026-09-14)